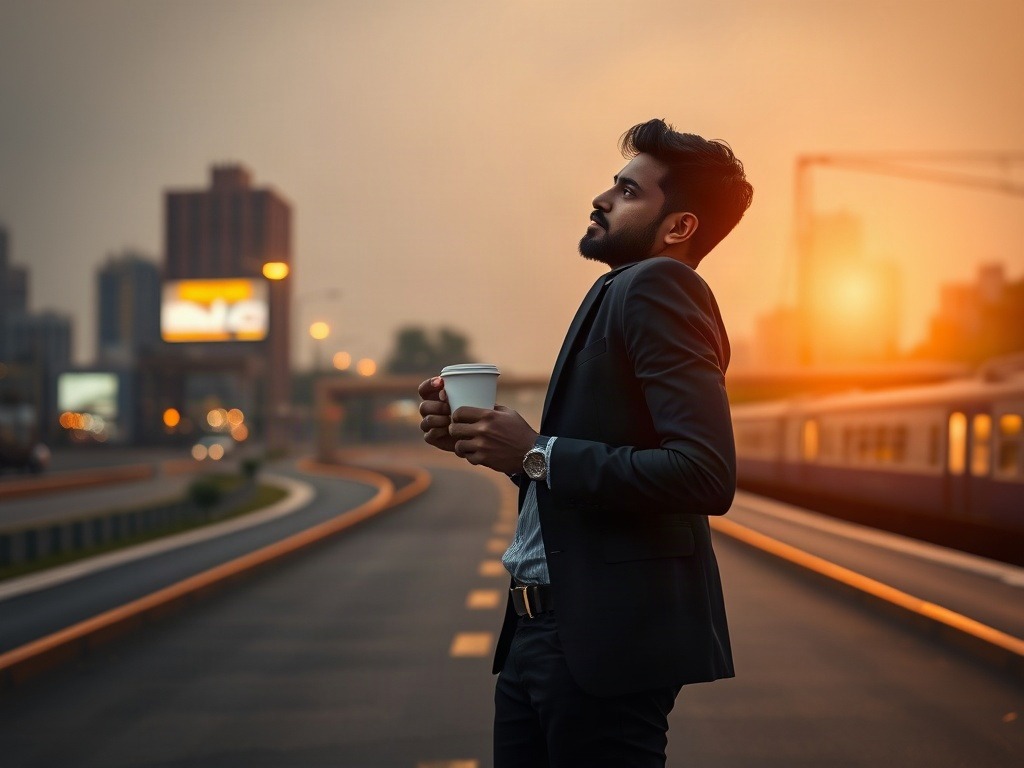
It was a Tuesday morning in March. I was sitting in the Kalyan railway station waiting area, coffee getting cold in my hand, staring at my phone. Twenty-eight years old. Three years into a data analyst role at Morningstar. Good salary. Decent benefits. A 90-minute commute each way that was slowly eating my soul.
My friend Priya texted: "Still coming to the meetup tonight?" It was a writing workshop for people thinking about freelance content work. I almost said no. I almost said, "I'm too settled now. Too old to restart." But I went anyway.
That night changed something. Not because I immediately quit and became a writer (spoiler: I didn't). But because I realized that the fear in my head — the one telling me that switching careers in your late 20s is reckless, unstable, something only 22-year-olds do — was completely made up.
Here's what I've learned over the last two years of genuinely exploring a transition while still working full-time: your late 20s are actually the perfect time to switch careers. Not in spite of your responsibilities and stability — but because of them.
The Myth That's Holding You Back
There's this story we tell ourselves: the right time to change careers was at 22, when you had no mortgage, no dependents, no "real" obligations. Now that you're 26, 27, 28? The window has closed.
This is nonsense. And I say that as someone who studied Economics — where we're trained to think in terms of opportunity costs.
The actual opportunity cost of switching careers in your late 20s is lower than you think. Here's why:
You Have Credibility Your 22-Year-Old Self Didn't
When you're applying for a role in your new field at 28 instead of 22, you're not starting from zero. You have work experience. You understand how to show up, deliver, handle pressure, and work with teams. Your previous career wasn't wasted — it was training ground.
I was terrified that leaving data analysis would mean someone would see me as a generalist, unfocused, someone who "couldn't commit." Instead, I've found that when I talk to editors and writers about my background, they ask questions like, "How did you approach data storytelling?" or "Did you ever notice patterns in how people engage with financial content?" The answer is yes — lots of patterns.
Your previous role gives you unfair advantages in your new field. Exploit that.
You Actually Have the Money to Take Risk
At 22, you might have earned ₹20-25 lakhs. At 28, if you've been progressing normally, you're probably earning ₹40-60 lakhs (or more). This is crucial. Your expenses probably haven't doubled, right?
That gap — the difference between what you earn and what you spend — is your transition buffer. It's not massive, but it's real.
I have about 18 months of expenses saved in a fixed deposit at ICICI Bank. It's not enough to quit tomorrow, but it's enough to take a role that pays 20% less, or to pick up freelance work on weekends without panicking. At 22, that wasn't possible.
The Framework That Actually Works
Okay, so the myth is busted. But how do you actually switch without sabotaging your current stability?
The answer is not to quit dramatically. The answer is to run a test.
Phase One: The Parallel Path (3-6 months)
Don't quit your job yet. Instead, spend 5-8 hours a week exploring the new field while keeping your current role.
This was my approach. I kept my full-time data role at Morningstar. But I started:
- Writing one article every two weeks on personal finance for indie publications (no payment — just portfolio building)
- Taking a Substack course (₹2,500 one-time)
- Attending writing meetups twice a month in Mumbai
- Reading 2-3 books on financial writing every month
The goal here isn't to become an expert. It's to answer three questions: Do I actually enjoy this? Can I do this well enough that someone would pay me? Is this the real thing or just the "grass is greener" feeling?
By month three, I had written 8 pieces. One had 2,000 reads on LinkedIn. I wasn't getting paid, but I was learning who my audience was and how I worked. More importantly — I knew this wasn't a fantasy. I could actually do this.
Phase Two: The Credibility Sprint (6-12 months)
Once you know you're serious, stop treating this like a hobby and start treating it like a second job.
I moved to 10-12 hours a week. I pitched to actual publications. Most rejected me. Some took me. I wrote for MoneyControl, The Quint's Fintech section, and a couple of smaller finance blogs. Payment was terrible at first — ₹1,500-3,000 per piece. But the clips started to matter.
This phase is uncomfortable. You're working 50-55 hours a week total. Your social life takes a hit. You stop going to movies on weekends. You miss some friends' weddings.
But here's what's happening: you're building proof. Proof to employers, yes. But more importantly, proof to yourself.
And honestly? It's not as brutal as it sounds. My commute became writing time (I'd work on outlines on the train). My lunch breaks became networking calls with editors. It's possible to compress this phase if you're intentional.
Phase Three: The Bridge Role (Optional but Smart)
You don't have to go from "full-time data analyst" to "full-time freelance writer" in one leap.
Many people benefit from a middle step: a role that's closer to their new field, pays decently (maybe 10-20% less than current), and allows 3-4 days a week of freelance work on the side.
For me, that looks like potentially transitioning into a "Insights & Content" role at a fintech company, where I'd use my data skills to inform financial writing and strategy. I haven't made this move yet, but it's the shape of the next step.
This phase is optional. Some people go full-time freelance directly. But I'm recommending it because it's the least risky path, and in your late 20s, you've already proven you can take risk — what you need now is compound growth.
What You'll Actually Lose (And Why It Might Be Worth It)
Let's be honest: there are real costs to this. Not everything is gained.
You will lose stability. Not immediately, not catastrophically. But the path becomes less linear. Your salary might dip. Your growth trajectory at your current company obviously stalls because you're not fully invested.
You will lose time with your family and friends. Seriously. I used to game on Friday nights. I don't anymore. I write instead.
You might lose confidence temporarily. I had a stretch (month 8 of the parallel phase) where I submitted 4 pitches and got 3 rejections. I thought, "Maybe I'm not actually good at this. Maybe I should stop."
You could lose money. If you take a lower-paying role in your new field and the income doesn't recover for 2-3 years, you're looking at ₹15-30 lakhs in foregone earnings. That's a car. That's a wedding fund. That's real.
The question isn't whether these costs are real. They are. The question is: are they worth what you're gaining?
For me? The cost is worth it because I can feel my energy shifting. I'm no longer draining myself in something that doesn't fit. I'm building something that actually excites me. And yes, I'm taking longer to get there — but I'm getting there.
The Practical Money Moves
All of this is theoretical unless you handle the money side correctly. Here's what I did, specifically:
| Money Move | Why It Matters | What I Did |
|---|---|---|
| Build a Transition Fund | Removes panic. Let's you make decisions from clarity, not desperation. | Moved ₹4 lakhs into a separate FD. Didn't touch it for a year. Now it's my safety net. |
| Track Freelance Income Separately | Shows you if your new path is actually viable. You need real numbers, not hopes. | Created a separate Groww account for freelance earnings. After 12 months, I had earned ₹58,000 — not enough to live on, but real proof. |
| Lower Your Monthly Burn Rate | If you're working 55 hours, you have less time to spend money anyway. Intentionally cut expenses. | Cancelled my gym membership (I wasn't going). Stopped eating out on weekdays. Saved ₹15,000/month this way. |
| Keep Health Insurance Non-Negotiable | One health crisis derails everything. Don't be stupid here. | Stayed on Morningstar's insurance. Also bought a ₹5 lakh personal health policy (Star Health, ₹3,500/year) just in case. |
| Don't Touch Your Investments | This is not the time to liquidate your Zerodha portfolio or raid your Provident Fund. You need that compound growth. | Actually increased my SIP by ₹500/month. Forced myself to think long-term even while taking short-term risks. |
The Questions You Need to Answer First
Before you start any of this, I want you to answer these questions honestly. Not for me — for you.
Is This Desire Based on Reality or Fantasy?
There's a difference between "I want to leave my job" and "I want to do X instead." The first is avoidance. The second is direction.
I didn't leave my data role because I hated it. I left (well, am leaving) because I found something I'm more drawn to. That's different. Spend a month actually doing the thing you want to do before you commit to switching.
Can You Handle 12-18 Months of Discomfort?
Not weeks. Not months. A solid year to a year and a half of working 50+ hours, saying no to things you enjoy, and feeling uncertain.
If the answer is "maybe" or "I don't think so," then your plan needs to be different. Bridge roles. Slower transitions. That's okay.
What's Your Financial Reality?
Not your fantasy budget. Your actual monthly spend. How much you save. How much you have saved. What your family depends on you for.
If you're sending ₹30,000 home to parents and have ₹2 lakhs in savings, a dramatic career change is riskier for you than someone with ₹20 lakhs saved and no dependents. Tailor your approach accordingly.
My Perspective
I studied Economics at university, and there was this moment in an Industrial Organization class where my professor discussed "switching costs" — the cost of moving from one product to another, one job to another. She said something I didn't fully understand then: "The best time to switch is when switching costs are actually visible, because that means you're being realistic."
At 22, I didn't see my switching costs clearly. I just saw infinite potential. At 28, I see them clearly — the salary gap, the time investment, the risk to stability. And you know what? That clarity makes the switch more possible, not less.
I was wrong about a lot of things. I used to think switching careers meant you were flaky or indecisive. I thought real adults stayed in one lane. I thought the "right" path was to climb a single corporate ladder until retirement.
What surprised me was how common this is. I've talked to 15+ people in the last year doing exactly this — writers in tech roles, designers in operations, software engineers trying sales. It's not unusual. It's modern.
What I'd do differently? I'd have started sooner. Not because it would be faster — the timeline would be the same. But because I'd have had more time to figure out what I actually want before I "had to" transition. I'd have run Phase One at 26 instead of 28. The principles are the same, but time is a gift when you're making fundamental changes.
Final Thoughts
Your late 20s are not too late. They're actually the sweet spot — you have enough stability to move thoughtfully, enough time to recover if things don't work out, and enough energy to push hard when needed.
The myth is that career switching is for young people with nothing to lose. The reality is that career switching works best when you have something to protect — your financial stability, your credibility, your relationships.
You don't need to quit tomorrow. You don't need to make a dramatic choice between your current life and your dream. You need a framework, a timeline, and the guts to spend a year doing two things at once.
If you're thinking about this, start with Phase One. Spend 5-8 hours a week on the thing you're curious about. See if it's real. See if you can do it. See if you want it.
That Tuesday morning when I walked into the writing workshop, I wasn't starting a new career. I was just showing up to see what would happen. Two years later, I'm still mostly a data analyst. But I'm also a writer now, building something that feels like mine.
Your late 20s aren't too late. They're exactly on time.
Dattatray Dagale
Data Analyst • Blogger • Mumbai
I'm a data analyst from Kalyan, Maharashtra, working at Morningstar. I write about personal finance, career growth, and everyday life for Indian millennials — the stuff I wish someone had told me earlier.
Written by Dattatray Dagale • 06 October 2026





0 Comments