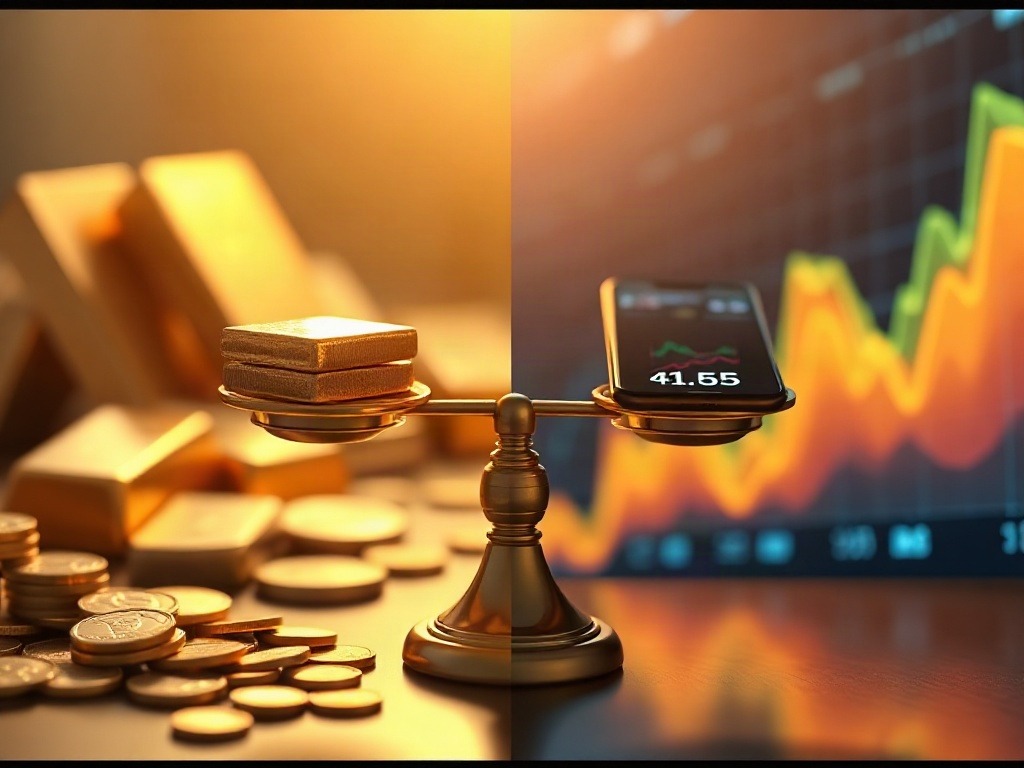
I remember standing in front of my grandmother's almirah in 2021, staring at her gold jewellery while she told me — for the hundredth time — that gold is the only real investment. I was 26, freshly into my first serious job at Morningstar, earning ₹45,000 a month, and I had ₹2 lakhs saved up. She wanted me to buy gold. My brain wanted stocks.
I did something stupid. I split it. ₹1 lakh into gold (via a jewellery shop in Kalyan, paid 4% making charges like an idiot), and ₹1 lakh into an index fund. Three years later, I have the actual numbers. And they're messier than I expected.
Here's what actually happened — and why the gold vs stocks question isn't as simple as either side makes it sound.
The Setup: My Real Numbers
Let me be transparent about this.
Gold side: ₹1 lakh invested in gold in March 2021. I still have it (physically, in that almirah — secure but also terrifying because I'm paranoid about theft). Gold was around ₹47,000 per gram back then.
Stocks side: ₹1 lakh into Nifty 50 index fund through Zerodha (Motilal Oswal Nifty 50 fund, direct plan, because commission matters when you're earning ₹45k/month). No additional investments. No SIPs. Just let it sit.
I chose these two deliberately because they're what most Indian millennials actually consider — not crypto, not real estate, not derivative trading. Gold and index funds. The basic choice.
March 2021 Snapshot
- Gold: ₹1,00,000 (approximately 2.13 kg at 4% making charges)
- Nifty 50 Index Fund: ₹1,00,000 (units purchased at NAV ₹295.48)
- My salary: ₹45,000/month
- Rent in Mumbai: ₹18,000/month (yes, I was splitting a 1BHK in Kalyan)
March 2024 Reality
- Gold: ₹1,78,000 (valued at current market rate of ~₹83,000/gram)
- Index Fund: ₹2,41,000 (current NAV ₹719.32, plus reinvested dividends)
- My salary: ₹78,000/month (after promotions and job changes)
- Rent in Mumbai: Same apartment, still ₹18,000 — upgraded my lifestyle elsewhere instead
That's a 78% return on gold vs 141% return on stocks. Over three years. Without any additional money invested.
But here's where it gets complicated.
Why Gold Won't Leave Our Heads (And Shouldn't)
My grandmother wasn't wrong. She was just incomplete.
And honestly? I've watched enough Morningstar data and client portfolios to understand why Indians obsess over gold in a way that Americans obsess over stocks.
The Actual Reasons We Buy Gold
1. It's not correlated with our salary or the market. During COVID lockdowns in 2020, when I was terrified about my job, gold didn't care. It just existed. My salary could disappear tomorrow, but that gold in the almirah would still be worth something. Stocks, meanwhile, crashed 35% in March 2020. For someone whose income was already shaky, that was genuinely scary.
2. It's a real thing you can hold. I can touch my gold. I can show it to my mother. I can, worst case, sell it to a jeweller on MG Road in Mumbai tomorrow and have cash. A NAV number on my Groww app? That feels abstract until I actually convert it. Behavioural economics calls this "tangibility bias" — we trust what we can see.
3. Emergency liquidity is actually better than it sounds. Yes, stocks are also liquid. But gold has a psychological advantage: it's genuinely emergency money. If you're in a crisis at midnight, you're not logging into Zerodha. You're going to your nearest jeweller (or pawnbroker) and getting cash in 20 minutes. I've seen this happen in my family. It matters.
4. It's culturally normalized. My mother asked me zero questions about my gold. She asked me approximately 47 questions about my stock fund. Questions like: "But what company is it?" (It's 50 companies, Ma), "What if they go bankrupt?" (They're not a single company, Ma), "Why do you not have it in your hand?" (That's the point, Ma). Cultural trust matters, even if it's not logical.
The mistake most people make? They think it's either/or. Gold OR stocks.
It's not.
The Math (Without the BS)
Let me show you how I actually think about this as a data analyst, stripped of ideology.
Time Horizon is Everything
If you need money in the next 2-3 years: don't use stocks. Full stop. Gold is fine. Bonds are better. Fixed deposits are honestly underrated. A three-year FD from HDFC Bank still gives you 6.5% with zero volatility. You won't get rich, but you won't lose sleep either.
But if your time horizon is 10+ years, and you're just going to ignore your portfolio (the way I'm ignoring my index fund most days), stocks are mathematically going to win. That's not opinion. That's data. Every 10-year rolling return in the Nifty since 1996 has beaten gold. Every single one.
Inflation Adjustment Changes Everything
Remember: ₹1 lakh in 2021 is not the same as ₹1 lakh in 2024. Inflation in India has been roughly 6-7% annually. So my ₹1 lakh in gold, even though it's now ₹1.78 lakh nominally, only gained about 78% in real terms. Minus the 4% making charges I paid upfront, I'm actually at about 66% real return.
My index fund, at 141% return, sounds better. But after inflation, it's still roughly 103% real return.
Not dramatically different. But still 37 percentage points better.
Over 30 years? That's the difference between ₹50 lakhs and ₹2.5 crores. Compounding is actually insane.
| Investment | Initial Amount (2021) | Current Value (2024) | Nominal Return | Real Return (Inflation Adjusted) | Effort Required |
|---|---|---|---|---|---|
| Gold (2.13 kg) | ₹1,00,000 | ₹1,78,000 | +78% | +66% | Low (but requires secure storage & insurance) |
| Nifty 50 Index Fund | ₹1,00,000 | ₹2,41,000 | +141% | +103% | Very low (set and forget) |
| HDFC Bank FD (3 years, rolled) | ₹1,00,000 | ₹1,65,000 | +65% | +53% | Very low (guaranteed) |
The table above is what I actually show to friends who ask me this question. Numbers don't argue.
The Hidden Costs (And Why My Gold Buying Was Dumb)
Here's something nobody talks about honestly: gold has costs that feel invisible because they're paid upfront.
I paid 4% making charges. That's standard in retail jewellery shops. ₹4,000 gone on day one, before gold even started appreciating.
Some jewellers also charge for "wastage" (₹2,000 in my case). So really, I started -6% in the hole from day one.
If I want to sell that gold later, I'll pay selling charges too. Expect another 2-3%. So I'm realistically looking at ₹1.73 lakh when I sell, not ₹1.78 lakh.
Meanwhile, my index fund has a 0.23% expense ratio. One-time. No hidden charges, no wastage, no making, no selling friction. I just sell when I want and money hits my account in T+2 days.
Over long time horizons, this compounds into a massive difference.
Plus: I have to insure my gold (₹100-200 per year). No insurance needed for my digital portfolio. I have to store it securely (paranoia included). Digital portfolio is technically safer because there's no single point of failure.
When Each Actually Makes Sense (Honest Answer)
Buy Gold If:
- You genuinely cannot sleep with stock market volatility. This is real. Your mental health matters more than a 2% extra return. Seriously.
- You need emergency cash within 2 years and don't trust yourself not to panic-sell stocks in a market crash.
- You're buying jewellery anyway (wedding, family tradition). Then you're not making a financial choice — you're making a consumption choice. That's different.
- Your portfolio is already weighted heavily toward stocks and you want diversification. A 10-15% gold allocation is insurance, not investment.
- You're in a country with currency instability or capital controls (not India, but relevant in some contexts). Gold is portable wealth.
Buy Stocks (Index Funds) If:
- Your time horizon is 10+ years. This is non-negotiable. Don't invest in equity if you need the money in 5 years.
- You can tolerate 30% portfolio swings in bad years without checking the app every day.
- You have a stable income and you're in the accumulation phase (ages 22-45 for most of us). Dollar-cost averaging smooths volatility.
- You genuinely don't care about the money. Indifference is a superpower in investing. I check my portfolio maybe once every 4 months. That's why it works.
- You want to actually build wealth, not just preserve it. This is the key distinction.
My Perspective
At Morningstar, I spend time looking at portfolio data of people across income levels. There's a pattern: people who actually got rich owned both, but weighted toward stocks when young, and shifted toward gold/bonds as they aged (past 50). That's sensible.
The surprising part? The people who got wealthy weren't smarter about picking the right investment. They were just boring. They stuck with one thing for 20+ years. That's it.
Gold makes you feel safe. Stocks make you feel smart. In reality, feeling safe while you're young is the expensive mistake. You have 40 years of income ahead. You don't need safety from your portfolio at 26 — you need growth.
I used to think gold was "for people who don't understand investing." Now I think it's for people who understand psychology. I was wrong about dismissing it. But I was also right about my 1 lakh going into stocks instead of gold — that's built a much bigger corpus.
If I could redo it, I wouldn't split it. I'd put ₹85,000 in the index fund and ₹15,000 in gold, psychologically. That's honest.
Final Thoughts
The gold vs stocks question isn't really about returns. It's about who you are as a person.
Are you the type who can ignore a portfolio for 10 years? Buy stocks.
Are you the type who loses sleep at 3 AM checking if markets crashed? Buy gold, or at least keep it as your "safety" allocation.
Honestly, the best investment is the one you'll actually stick with. I know people who bought gold and panicked-sold it in 2013 at a loss. I know people who bought stocks at the peak in 2021 and became convinced they're ruined for life (they're not — they were just early). Your behaviour matters more than the instrument.
If you're reading this from Mumbai, or Kalyan, or anywhere in India, and you're 22-35 with a stable job? Put money in stocks now. You have time. The math is clear. But allocate some emergency gold too — maybe 10% of what you invest in stocks. Sleep better. Live longer. Both matter.
And for God's sake, if you're buying physical gold, don't pay 4% making charges. Go digital. We're living in 2024, not 1994.
You've got this. And honestly? Three years from now, whether you pick gold or stocks, the fact that you're thinking about it at all puts you ahead of most people your age.
Dattatray Dagale
Data Analyst • Blogger • Mumbai
I'm a data analyst from Kalyan, Maharashtra, working at Morningstar. I write about personal finance, career growth, and everyday life for Indian millennials — the stuff I wish someone had told me earlier.
Written by Dattatray Dagale • 27 September 2026




0 Comments