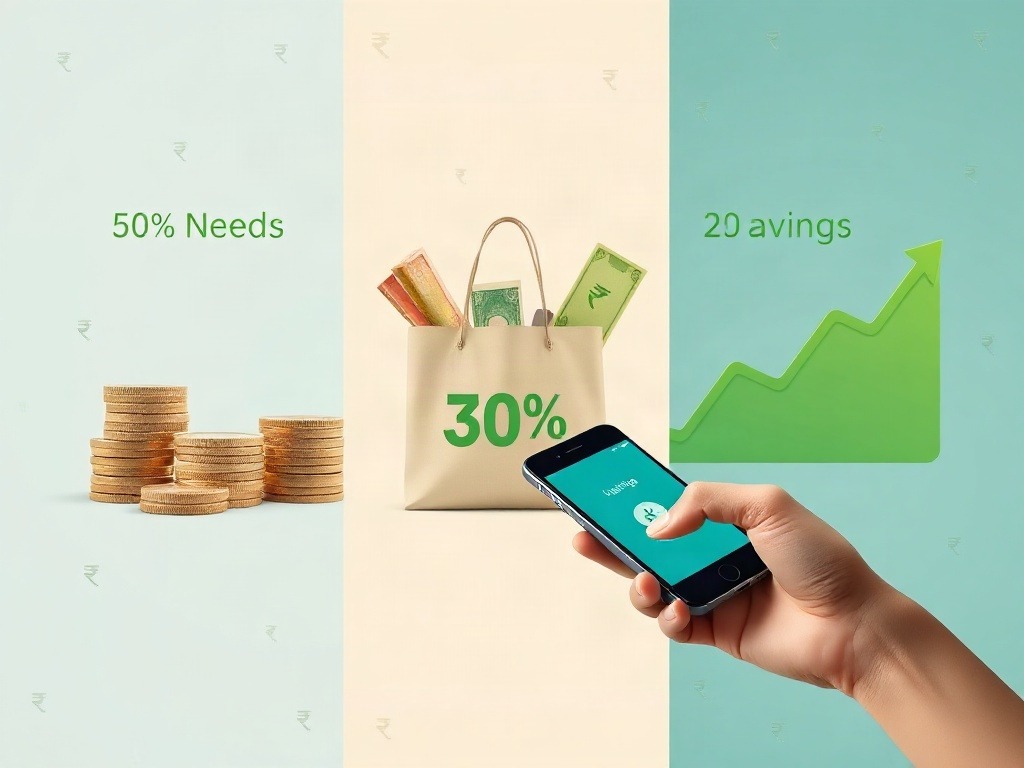
The first time someone explained the 50-30-20 rule to me, I was sitting in a cafe in Vile Parle waiting between meetings. My colleague (one of those frustratingly organized types) pulled up a spreadsheet on her phone and said, "Just split your salary into three buckets. Fifty percent needs, thirty percent wants, twenty percent savings. Done."
I nodded. It sounded so... clean. So simple. Like a formula that would finally make sense of the chaos I created every month, spending like I was earning double what I actually made.
Spoiler: it wasn't that simple. But here's what I learned after two years of actually trying to live by it, breaking it, rebuilding it, and figuring out what works when you're earning in INR, living in a Mumbai suburb, and commuting 45 minutes each way.
The 50-30-20 Rule Actually Makes Sense (But You Need to Understand Why)
Let's start with the basics, because most people skim this part and miss the point entirely.
50% for Needs: Essential expenses — rent, utilities, groceries, insurance, commute costs, phone bills. Things you'd struggle without.
30% for Wants: The stuff that makes life enjoyable but isn't essential — eating out, subscriptions, gadgets, hobbies, travel.
20% for Savings & Investments: Your future self. Emergency fund, mutual funds through Groww, fixed deposits, whatever aligns with your goals.
The reason this framework exists isn't because some finance guru pulled it from thin air. It's based on real human behavior and real financial limits. When you spend more than 50% on needs, you're essentially trapped. You have less flexibility. You can't breathe.
I used to spend 65% on needs alone — rent took 30%, commute and food another 20%, utilities and subscriptions another 15%. That left me with only 35% for everything else. And honestly? That's when I started using credit cards irresponsibly. The 50-30-20 rule forces you to confront that problem.
Why This Rule Matters for Indian Millennials Specifically
Here's where context matters. In India, our biggest constraint is usually housing. A decent 1BHK in Mumbai, Bangalore, or Pune will eat 30-40% of your salary before you even think about food. Add travel (whether it's EMI on a two-wheeler or daily commute costs), and you're already at 45-50% just on necessities.
The traditional 50-30-20 rule assumes you have some flexibility on the needs side. But if you're paying 35% rent, 8% utilities, 4% travel, and 5% groceries, you're already at your 50% cap. One medical emergency and the whole thing collapses.
This is why the rule isn't gospel. It's a starting point.
The Real Value Isn't in Perfection — It's in Visibility
What changed for me wasn't following the 50-30-20 rule exactly. It was tracking where my money actually went for three months. Not budgeting. Tracking.
I used a simple Google Sheet (still do, honestly — overkill tools like YNAB or PocketGuard feel like they're trying too hard). For three months, I logged every transaction. Coffee, CRED payment, Zomato order, movie ticket, everything.
And then I looked at the numbers.
I was spending 22% on food and dining alone. Subscriptions? 6% (Netflix, Spotify, Kindle Unlimited, Amazon Prime, a meditation app I never opened). Wants were consuming 38% of my salary, not 30%. And my savings rate was 8%, not 20%.
The rule didn't change overnight. But seeing it in numbers — ₹4,500 a month on eating out when I could've saved ₹54,000 a year — made it real in a way budgeting apps never could.
The Indian Reality of 50-30-20
Here's the thing about importing Western financial wisdom into the Indian context: it sometimes works, sometimes doesn't, and sometimes requires creative adaptation.
What Changed for Me When I Stopped Being Rigid
After three months of strict tracking, I tried being aggressive with the 50-30-20 split. It lasted six weeks.
The problem was that I was living alone in Kalyan (my parents are in a different city), commuting to Mumbai for work at Morningstar, and trying to stick to rules that assumed stability. Some months I had unexpected expenses — a dental root canal (₹8,000), my laptop's hard drive died (₹6,000), car maintenance (₹3,500).
Suddenly I was overshooting my needs bucket by 8-10%, cutting into savings, and feeling like I'd failed.
I realized I was being stupid. The rule isn't a law. It's a guideline.
What I do now instead:
Target 50-30-20, but aim for a monthly average of 50-30-20. Some months might be 52-28-20. Other months 48-32-20. As long as when I look at the quarter or six months, I'm hitting those percentages, I'm on track.
Build a buffer within your needs. That root canal? It's a need. But it's an irregular need. I now keep 3-4% of my salary as a "contingency within needs" — separate from my emergency fund. This is the difference between having a safety net and pretending you don't need one.
Let wants flex downward, not upward. The 30% for wants is a ceiling, not a target. If I spend 22% and save 28%, that's better than hitting exactly 30%. Most people interpret this backwards — they think "I have 30% for wants, so I should spend all of it." That's not how margins work.
Practical Numbers (Using Real INR Amounts)
Let me make this concrete. Let's say you're earning ₹75,000 monthly (a pretty standard salary in Mumbai for someone 25-28 years old working in corporate or tech).
50% Needs = ₹37,500
- Rent: ₹18,000 (a 1BHK in Kalyan or Thane)
- Electricity, water, internet: ₹2,500
- Groceries & cooking at home: ₹5,000
- Commute (fuel or train pass): ₹3,000
- Phone, insurance: ₹2,000
- Contingency: ₹7,000
30% Wants = ₹22,500
- Dining out, food delivery: ₹6,000
- Entertainment (movies, hobbies): ₹4,000
- Subscriptions: ₹2,000
- Shopping, clothes, misc: ₹5,000
- Travel, weekend trips: ₹5,500
20% Savings & Investments = ₹15,000
- Emergency fund buildup: ₹5,000
- Mutual funds (via Groww): ₹6,000
- Stocks/FDs/other: ₹4,000
Is this easy to maintain? Not always. Do people actually do it? Some do, some don't. But it's a realistic framework for someone earning ₹75,000 in a tier-1 city.
| Category | Target % | Amount (₹75k salary) | Real-Life Adjustment |
|---|---|---|---|
| Needs | 50% | ₹37,500 | ₹35,000–₹40,000 (includes contingency) |
| Wants | 30% | ₹22,500 | ₹15,000–₹25,000 (very flexible) |
| Savings & Investments | 20% | ₹15,000 | ₹10,000–₹20,000 (non-negotiable minimum: ₹10k) |
How to Actually Implement This (Without Losing Your Mind)
Step 1: Track First, Budget Later
I cannot stress this enough. Most people fail at budgeting because they create a budget before they understand their actual spending patterns.
Spend 30 days logging every transaction. I use my bank app and a Google Sheet, updating it once a week. Some people swear by Money View or Wallet apps. Use whatever you'll actually check.
Don't judge yourself during this period. Just observe.
Step 2: Use Automation to Separate Your Money
After you've tracked for a month, set up automatic transfers on the day you get paid.
This is non-negotiable. If you keep all your money in one account, you'll spend it. Your brain doesn't understand percentages. It understands "money available."
What I do:
Salary hits Account A (main account) → On day 2 of every month, I transfer:
- ₹15,000 to Account B (savings/investment account at a different bank)
- ₹22,500 to Account C (wants account — where I keep my "fun money")
- The remaining ₹37,500 stays in Account A (needs account)
This takes about five minutes to set up as a recurring transfer. And it means I never even see the savings money in my main account. I can't spend what I don't see.
Pro tip: Use a high-interest savings account for your savings bucket (HDFC Bank's eAura or ICICI's digital savings account give 3-4% interest). It's not much, but it's something. And it psychologically feels different from a current account.
Step 3: Invest the Savings Immediately
Once the ₹15,000 hits your savings account, don't let it sit there. Move it to a mutual fund through Groww or Zerodha within 3-4 days. Or buy an FD if you're risk-averse.
The goal is to remove the temptation. Money sitting in a savings account is psychologically easier to dip into than money in a mutual fund.
For context, a ₹15,000 monthly investment over 10 years at a 12% CAGR (realistic for equity mutual funds) turns into ₹32 lakhs. That's not nothing.
My Perspective
I spent my first year of earning post-graduation completely without a budget. I'd check my account occasionally and get a little shock at how little was left. My second year, I was obsessive — spreadsheets, tracking every ₹50 coffee, feeling guilty for buying a shirt.
Now, on my commute from Kalyan to Bombay Central (I take the local train most days), I listen to podcasts or read. Some mornings I overhear people stressed about money, and I remember being that person. The 50-30-20 rule isn't revolutionary. But it gave me a framework to stop stressing and start acting.
What surprised me? It wasn't about discipline. It was about automation. The months I was disciplined but didn't automate transfers? I failed. The months I set up transfers and forgot about them? I succeeded. That one insight changed everything.
And honestly, I still break the rule some months. Last month I spent 34% on wants because I went on a trip to Lonavala. But I look at the quarterly average, and I'm still on track. That's the game — not perfection, but consistency over time.
Final Thoughts
The 50-30-20 rule isn't a secret formula. It's just math that makes sense. And honestly? If you can stick to it — even loosely — you're already ahead of most people.
The real challenge isn't understanding the rule. It's implementing it. It's setting up those automatic transfers. It's saying no to that expensive dinner when you've hit your wants quota. It's investing the savings instead of letting it accumulate in a savings account.
But here's what I've learned: once you do it for a few months, it stops being hard. Your brain adjusts. You start seeing your account balance grow, and that becomes its own motivation. The guilt disappears. The stress eases. You sleep better.
Start tracking this week. Just for 30 days. See where your money actually goes. Then come back to this rule and adjust it for your life. Not the other way around.
You've got this.
Dattatray Dagale
Data Analyst • Blogger • Mumbai
I'm a data analyst from Kalyan, Maharashtra, working at Morningstar. I write about personal finance, career growth, and everyday life for Indian millennials — the stuff I wish someone had told me earlier.
Written by Dattatray Dagale • 26 September 2026




0 Comments