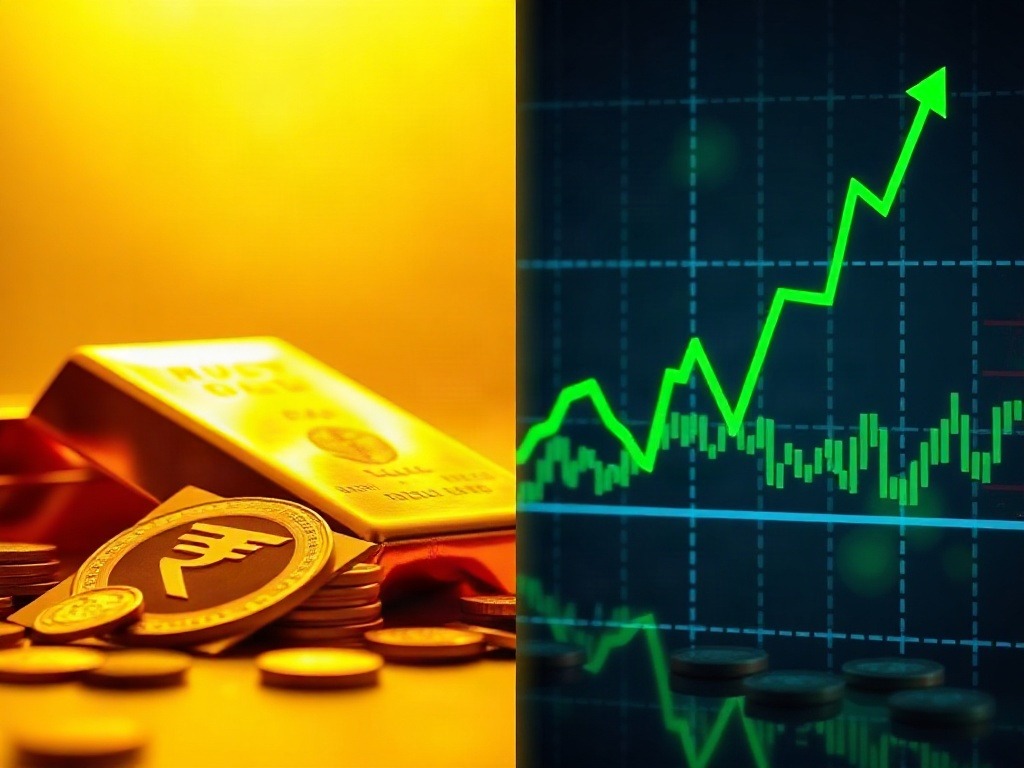
Dear younger me (or maybe you, if you're sitting in a local train from Kalyan to Mumbai right now),
It's 6:47 AM. You're holding a lukewarm chai from the station vendor, your phone is at 12% battery, and somewhere between Dombivali and Thane, a thought hits you: Should I invest ₹50,000 in gold or the stock market?
Your mom probably told you gold is safe. Your uncle swears by it. Your dad might have bought some during the 2008 crash. And honestly? I used to think the same way. But after five years of working at Morningstar, analyzing numbers, and watching my own money move around, I need to tell you something your well-meaning relatives won't.
Gold and stocks aren't really competitors. They're not even in the same race. And once you understand why, you'll stop agonizing over this choice.
Why We're Obsessed With Gold (And Why That's Mostly Emotion)
Let me start here: I get it. Gold feels safe. It's tangible. You can touch it. Your grandmother wore it. During the pandemic, when everything was chaos and uncertainty, gold prices shot up 25% in just a few months. It's like a security blanket wrapped in emotional inheritance.
But here's what I've realized—that feeling of safety is doing most of the selling job, not the actual returns.
The Safety Myth That Costs You Money
Gold doesn't generate income. It just sits there. You buy an ounce at ₹60,000, and five years later, it might be worth ₹75,000. That sounds nice until you do the math: that's roughly 4.6% per year. But inflation in India runs at 5-6% annually. Which means you're actually losing purchasing power. Your ₹75,000 buys less than it did five years ago.
Compare that to a simple Nifty 50 index fund over the same period—you'd have made 10-12% per year on average. Yes, it fluctuates. Yes, some years it tanks. But over time, stocks beat gold. Not by a little bit. By a lot.
And yet we still buy gold because it doesn't scare us. It doesn't have days where it drops 5% and makes your stomach hurt. That's not actually a good reason to invest ₹50,000. That's just risk aversion dressed up as wisdom.
When Gold Actually Makes Sense
I'm not saying gold is useless. It's not. It's just useful for maybe 10-15% of your portfolio, and for very specific reasons.
Gold is a hedge. During geopolitical crises, bank failures, or currency crashes, gold tends to hold its value when other things collapse. It's also less correlated with stocks—when Sensex crashes, gold might go up. So if you keep 10% of your emergency fund in gold, that's not stupid. It's boring insurance.
But investing ₹50,000, expecting it to be your path to wealth? That's not a strategy. That's hope wearing a Hallmark card.
Why Stocks Terrify Us (But Shouldn't)
Here's the uncomfortable truth: stocks are volatile. I opened my Zerodha terminal on March 12, 2020, watched Nifty drop 13% in a day, and felt physically ill. My ₹2 lakhs felt like ₹1.7 lakhs. By August, it was ₹2.3 lakhs. By 2023, it was ₹3.8 lakhs.
That's not a fluke. That's how markets work.
When you invest in stocks—whether through direct equity, mutual funds via Groww, or ETFs—you're buying a piece of real companies. Reliance, TCS, Infosys, HDFC Bank. These aren't gambling chips. They're productive assets that generate profit, pay dividends, and grow over time. Gold doesn't do any of that. It just... exists.
The Time Horizon Matters More Than You Think
Here's where most people get it wrong: they compare a 1-year stock return with a 1-year gold return and conclude they're the same. They're not playing the same game.
If you need money in 6 months, don't buy stocks. That's not because stocks are bad. It's because you're using the wrong tool for the wrong timeframe. Gold, in that case, is actually better.
But if you have 10+ years before you need this money—and at 22-28 years old, most of us do—then stocks are objectively better. Not debatably better. Mathematically better. The data is absolute.
I have friends who bought gold in 2015 at ₹27,000 per 10g. Today, in 2024, it's ₹70,000 per 10g. That's 2.6x returns in 9 years. Sounds great, right? But ₹1 lakh in a Nifty index fund in 2015 would be ₹3.2-3.5 lakhs today. That's a bigger multiple. And it paid dividends along the way (which gold doesn't).
The Psychological Difference
Here's something nobody talks about: stocks teach you something gold never will. When you own stocks and watch them drop 15%, then recover, then hit new highs, you learn about volatility. You learn that crashes are temporary. You learn patience. You learn that panic-selling is the enemy.
Gold doesn't teach you anything. It's passive. You buy it, forget it, and hope it goes up. That's not building an investor mindset. That's just... hoping.
The Direct Comparison: Gold vs Stocks
Let me lay this out clearly so you can see what's actually different:
| Metric | Gold | Stocks (Nifty 50 Index) |
|---|---|---|
| 10-Year Average Return | ~4-5% per year | ~10-12% per year |
| Income Generation | None (Zero dividends) | Dividends (~1.5-2% per year) |
| Volatility | Low (Predictable) | High (Unpredictable short-term) |
| Beats Inflation? | Often just matches it | Consistently outpaces it |
| Effort Required | Minimal (Buy & Hold) | Minimal (SIP & Hold) |
| Tax Efficiency | Long-term gains taxed at 20% | Long-term gains taxed at 10% |
| Liquidity | Good (Sell anytime) | Excellent (Instant selling) |
| Emergency Fund Suitability | Better (No panic risk) | Risky (Might decline when needed) |
Look at that table. Really look at it. Stocks win on almost every metric except volatility and emergency fund suitability. And yet, we still hesitate.
How I Actually Approach This (My Real Strategy)
I'm not an absolutist about this. I don't think gold is evil or stocks are guaranteed. I think both have a place, just not an equal place.
Here's what my actual portfolio looks like right now:
70% Stocks — Mostly index funds (Nifty 50, Nifty Next 50, Sensex). Some direct equity in 4-5 companies I understand. This is my growth engine. I'm 32. I have 25+ years until retirement. Market crashes don't scare me because I'm not selling.
15% Debt Funds and Fixed Deposits — For stability and tax-efficient income. Liquid funds for emergencies.
10% Gold — Mostly as insurance. I own about 100 grams across digital gold and physical. If everything collapses, it's there. If it doesn't, I'm okay with it doing nothing because it's only 10%.
5% Everything Else — REITs, international stocks, experimental stuff. Learning money.
The 70% in stocks is why I've built actual wealth. The 10% in gold is why I sleep well on volatile days. They're not competitors. One is my engine. One is my seatbelt.
My Perspective
Here's where I'm brutally honest: I changed my mind on this about four years ago, and I'm still a bit annoyed at myself for taking so long.
I was having chai with a colleague from work—Priya, who works in the fixed income team at Morningstar. She mentioned she'd been telling her parents to shift 50% of their gold holdings to index funds. Her mom was horrified. "But what if the market crashes and we lose everything?"
Priya asked her a simple question: "Mom, in 30 years, has gold ever made you rich?"
The answer was no. It just maintained wealth. It never multiplied it meaningfully.
That conversation stuck with me because I realized I was giving the exact same advice to my younger cousins—play it safe with gold—without actually running the numbers. I was passing down fear, not strategy.
What surprised me most was how quickly the math became obvious once I looked at it directly. I wasn't just being conservative. I was being mathematically inefficient. And for someone who works in data analysis, that was embarrassing.
Now, I tell everyone the same thing: gold is fine for 5-10% of your portfolio. But if you're building wealth on a 22-35 year old's salary, stocks are non-negotiable. Not optional. Essential.
Final Thoughts
You don't have to choose between gold and stocks. You just have to choose proportions.
Start with stocks. Open a Groww or Zerodha account. Buy ₹10,000 in a Nifty 50 index fund. Set up an automatic ₹5,000 monthly SIP. Do this for 10 years without checking the app more than once a quarter. By the time you're 35, you'll have accumulated ₹6+ lakhs (without counting the growth, which will push it well beyond that).
Then, if it makes you feel secure, keep 10% of that in gold. But don't let gold be your primary strategy. That's like buying a car for its cup holders and ignoring the engine.
The train to Mumbai is almost pulling into CST. Your chai is cold. But your future doesn't have to be.
Start today. Seriously. Open the app right now.
You'll thank me in ten years.
Yours in compound interest,
Dattatray
Dattatray Dagale
Data Analyst • Blogger • Mumbai
I'm a data analyst from Kalyan, Maharashtra, working at Morningstar. I write about personal finance, career growth, and everyday life for Indian millennials — the stuff I wish someone had told me earlier.
Written by Dattatray Dagale • 26 October 2026






0 Comments